

SEC Disowns WayvePay Over Suspected Fraud as Dangote Refinery IPO Nears Deadline
The Securities and Exchange Commission (SEC) has warned Nigerians against investing through WayvePay, an online financial platform it says is not registered to solicit investments from the public or...
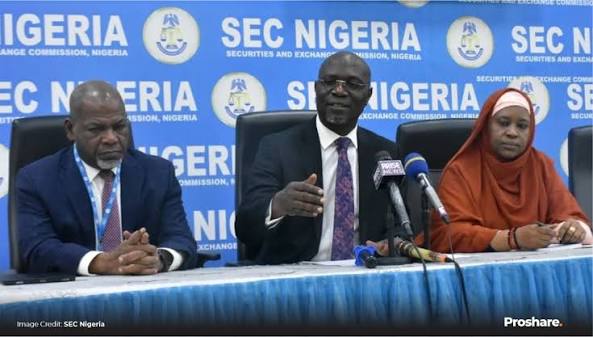
- The regulator’s warning exposes the risks of unverified digital investment channels, raising fresh questions about investor protection, fintech accountability and the integrity of Nigeria’s capital market.
The Securities and Exchange Commission (SEC) has warned Nigerians against investing through WayvePay, an online financial platform it says is not registered to solicit investments from the public or operate in any capacity within the Nigerian capital market.
The warning, contained in a notice signed by the Commission’s management on Friday, October 9, and published on its official website on Saturday, October 10, 2026, comes days after WayvePay advertised its purported role in providing customers access to the Dangote Petroleum Refinery and Petrochemicals initial public offering (IPO).
In the notice titled _“Suspected Fraudulent Activities of WayvePay”_, the SEC said the platform operates through a website, social media channels and a mobile application, but stressed that it has not authorised the company to conduct capital market activities.
The Commission advised Nigerians to refrain from investing through WayvePay or its representatives in connection with capital market transactions, warning that dealings with unregistered and unregulated entities expose investors to fraud and potential financial losses.
The development places renewed scrutiny on the intersection of digital banking, fintech-led investment distribution and the regulatory safeguards surrounding one of Nigeria’s most closely watched corporate share offerings.
The SEC’s notice establishes that WayvePay is not registered to undertake the specified capital market activities. It does not, by itself, establish that every service associated with the platform is fraudulent or that a criminal offence has been proved.
How the Dangote IPO brought WayvePay under scrutiny
The regulatory warning followed a newspaper publication dated October 6 in which WayvePay, described as the digital banking platform of Wayve Microfinance Bank, announced that it was making the Dangote refinery IPO accessible to its customers.
The timing is significant. The refinery’s public offering has attracted attention from retail investors seeking exposure to a major industrial asset, creating commercial opportunities for banks, fintech companies, investment platforms and other authorised intermediaries.
The SEC approved the refinery’s IPO to open on September 14, 2026, and subsequently advised investors to subscribe only through officially designated and approved receiving agents, subscription channels and platforms.
Its guidance specifically cautioned investors against transferring money to unauthorised entities, responding to unsolicited investment offers or relying on claims that a platform’s existence automatically makes it an approved subscription channel.
The distinction is crucial: an investment opportunity can be genuine while a particular intermediary advertising access to it remains unauthorised.
Consequently, the existence of an approved IPO does not automatically validate every website, mobile application, advertisement or payment channel claiming to facilitate subscriptions.
IPO deadline heightens the stakes
As of October 12, the Dangote refinery IPO is scheduled to close on October 13, according to reporting on the offer. The approaching deadline adds urgency to the SEC’s warning because investors may be more susceptible to pressure when they believe they have limited time to secure shares.
A short subscription window can encourage hurried decisions, particularly among first-time investors who rely on advertisements, social media posts and claims made by digital platforms rather than independently verifying an offer
However, urgency is not evidence of fraud in itself. The critical questions are whether the intermediary is authorised, whether the subscription channel has been approved for the particular offer, and whether payments are being made through the prescribed process.
The SEC’s intervention therefore serves a broader purpose than distancing itself from one platform. It reinforces the need to separate the legitimacy of an issuer and its securities offering from the credentials of the intermediaries seeking to distribute those securities.
What is the SEC’s responsibility?
The SEC is Nigeria’s principal regulator of the capital market. Its responsibilities include regulating securities offerings and market operators, supervising relevant capital market activities, enforcing applicable rules and protecting investors against misconduct.
Under the Investments and Securities Act 2025, capital market activities operate within a statutory framework intended to promote transparency, fair dealing and confidence in the market.
Registration is an important part of that framework. It enables the regulator to assess whether operators meet applicable requirements and brings registered participants within its supervisory and enforcement system.
For investors, this creates a channel through which they can verify an operator’s status and establish whether the business is authorised to perform the activity being advertised.
The WayvePay case illustrates why that distinction matters in an increasingly digital market. A platform may offer a convenient interface, display professional branding and advertise access to a recognised investment opportunity. None of those features independently establishes regulatory approval.
The SEC’s warning is therefore consistent with its investor-protection mandate. Nevertheless, the effectiveness of that mandate depends not only on issuing public notices but also on monitoring suspicious activity, investigating complaints, pursuing appropriate enforcement action and communicating verified information quickly enough to prevent avoidable losses.
Where unauthorised operators are found to have collected investors’ money, the response may also require cooperation with law-enforcement agencies, payment providers and other relevant regulators, depending on the facts and the applicable law.
Digital banking is not the same as investment authorisation
One of the central issues in the WayvePay controversy is the possibility that consumers may confuse digital financial services with permission to distribute securities.
A platform’s association with a microfinance bank, or its description as a digital banking service, should not be interpreted as blanket authorisation to conduct every kind of financial transaction.
Banking, payments, securities dealing, investment advice and the distribution of public offers can fall under different regulatory requirements. The precise obligations depend on the service provided and the capacity in which an operator acts.
This means investors must examine the specific activity being offered rather than rely solely on a company’s brand, business description or relationship with another financial institution.
It also places a responsibility on fintech businesses to explain their regulatory status accurately, identify the licensed entities involved in an investment transaction and avoid creating the impression that a service has received approval when it has not.
For regulators, the challenge is to ensure that innovation expands access to legitimate investments without creating gaps through which unqualified or unauthorised operators can reach the public.
A warning that follows earlier SEC action on the refinery offer
The WayvePay notice is not the first time the SEC has intervened over promotions associated with the Dangote refinery share offering.
On June 23, 2026, the Commission issued a cease-and-desist directive concerning misleading and manipulative solicitations and premature marketing relating to a purported refinery securities offering.
At that time, the SEC said no application for registration of the proposed IPO had been filed with or approved by the Commission. It directed affected market operators and digital platform promoters to stop unauthorised promotions and, among other measures, refund funds collected in connection with the purported offering
The subsequent approval of the refinery’s IPO in September represents a different stage in the regulatory process. The earlier directive concerned promotional activities undertaken before the offering had received the necessary approval; the later IPO was approved subject to the applicable procedures and authorised subscription arrangements.
That chronology matters. It demonstrates that regulatory approval is a formal process, not an assumption that can be inferred from publicity, a company’s commercial relationships or the appearance of an investment opportunity in the media.
It also shows why investors need to distinguish between an approved securities offering and any separate claim by a platform to provide access to it.
The risks investors face
Dealing with an unauthorised investment intermediary can expose consumers to several risks, although the precise risks in any individual case depend on the facts.
Money transferred to an unauthorised operator may be difficult to recover, particularly if it is moved through multiple accounts or payment channels.
Investors may be unable to establish whether an application has been submitted through an approved channel or whether shares have actually been allocated to them.
Customers who provide identification documents, bank details, passwords or other sensitive information through an unverified platform may face additional financial and privacy risks.
Where an operator falls outside the relevant regulatory framework, investors may find it more difficult to obtain regulatory assistance or resolve disputes through established capital market procedures.
The association of an advertised investment with a prominent company or a recognised public offering can make an unauthorised intermediary appear more credible than it is.
These risks explain why verification should precede payment, rather than follow it.
What investors should do no
The SEC has directed prospective investors to check the registration status of companies and entities offering investment opportunities through its official portals.
Investors can begin with the Commission’s registered fintech oprators directory and its capital market operators register.
They should also consult the official IPO prospectus and the list of approved subscription channels for the specific offer. Being registered in one capacity should not automatically be treated as authorisation to perform every other regulated activity.
Anyone who has already transferred money through WayvePay for an investment should preserve payment receipts, account statements, transaction references, advertisements and communications with the platform. They should contact their bank or payment provider promptly, report the matter to the SEC and seek guidance from the appropriate authorities.
Investors should avoid sending additional money in an attempt to recover an earlier payment without independently verifying the legitimacy of the request.
Importantly, the SEC’s notice should not be interpreted as proof that every customer transaction conducted through WayvePay is fraudulent. The relevant issue is the platform’s lack of SEC registration for the specified capital market activities and the resulting risks associated with using it for such transactions.
The wider challenge: expanding access without weakening safeguards
Digital platforms can play an important role in broadening participation in Nigeria’s capital market. They can reduce the practical barriers to investing, improve access to information and make it easier for retail investors to participate in public offers.
But convenience can also accelerate the spread of misleading promotions. Online advertising and mobile applications allow investment claims to reach large audiences quickly, while consumers may struggle to distinguish licensed operators from businesses whose regulatory credentials have not been established
The solution is not necessarily to restrict legitimate fintech participation. Rather, it is to ensure that digital distribution channels operate within clear rules, that approved subscription platforms can be verified easily, and that regulators respond promptly when unauthorised activities are identified.
The SEC also needs to communicate consistently about the status of public offerings, particularly where preliminary marketing, formal approval and subscription periods occur at different stages. Clear communication helps investors understand when an offer is legitimate, who may distribute it and where their money should go.
For fintech operators, compliance should be treated as a condition of sustainable growth, not an administrative hurdle to be addressed after customers have been recruited.
For investors, the lesson is equally direct: a familiar brand, a digital banking label or an advertisement linked to a prominent company is not a substitute for regulatory verification.
What happens next?
The SEC’s warning establishes a clear boundary: WayvePay is not registered by the Commission to solicit public investments or operate in Nigeria’s capital market.
The next questions concern the practical implications of that warning. These include whether investors have already paid money through the platform, whether any applications were submitted through approved subscription channels, whether affected customers have suffered losses and what further action the relevant authorities may take.
Those questions require verified information and, where appropriate, investigation. The public notice alone does not establish the answers.
Ultimately, the WayvePay episode is a test of how effectively Nigeria can protect retail investors as digital platforms become more prominent in financial services. The SEC’s intervention is an important warning, but investor protection also depends on enforcement, transparent subscription arrangements and the willingness of consumers to verify claims before committing their money.
As the Dangote refinery IPO approaches its scheduled closing date, the immediate priority is to ensure that investors distinguish the approved public offering from unauthorised channels claiming to provide access to it. In a market where digital convenience can rapidly amplify both opportunity and risk, that distinction is fundamental to public confidence.



No Comment! Be the first one.