

Nigeria’s Court of Appeal Faces Reported ₦9.6 Billion Salary Accountability Gap: Compliance, Fraud and Financial Crime Implications
Financial Accountability and Institutional Risk A reported ₦9.6 billion discrepancy involving staff salary funds at Nigeria’s Court of Appeal, under the leadership of Justice Monica Dongban-Mensem,...
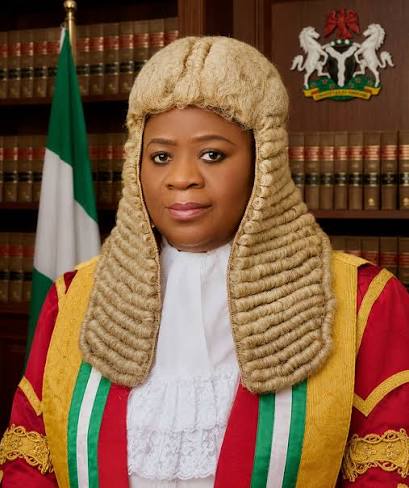
Financial Accountability and Institutional Risk
A reported ₦9.6 billion discrepancy involving staff salary funds at Nigeria’s Court of Appeal, under the leadership of Justice Monica Dongban-Mensem, raises significant questions about public-sector financial accountability, payroll integrity and institutional cooperation with investigators. The allegation suggests that the funds could not be adequately accounted for and that investigators were not provided with a satisfactory explanation.
The figure is substantial, but its precise nature remains unverified. The period covered, the number of employees involved, the underlying transactions and the status of any formal investigation require confirmation. Accordingly, ₦9.6 billion should be treated as an alleged accountability gap rather than a confirmed financial loss or proven case of fraud. An unexplained discrepancy may result from inadequate documentation, reconciliation failures, payroll manipulation or deliberate diversion; establishing which scenario applies requires documentary and forensic evidence.
Financial Exposure and Historical Context
The scale of the allegation is significant when considered against historical judicial-sector spending. A 2015 budget analysis reported that the Court of Appeal received an appropriation of approximately ₦11.10 billion. This included ₦1.214 billion for justices’ consolidated salaries, ₦2.699 billion for other personnel costs, ₦4.699 billion for overheads and ₦2.496 billion for capital expenditure. These historical figures provide context but do not establish the validity of the current salary-fund allegation.
Separately, a 2017 report concerning federal courts cited audit findings involving approximately ₦4.8 billion in expenditure that could not be properly accounted for across multiple judicial institutions during 2012–2015. Reported issues included missing supporting documents, tax irregularities and inadequately verified supplies. These findings illustrate the recurring importance of robust financial controls within public institutions, although no direct connection to the current allegation has been established.
Fraud Risks and Investigative Priorities
From a forensic accounting perspective, the principal concern is whether the alleged discrepancy reflects control weaknesses or intentional financial misconduct. Investigators should reconcile approved payroll registers with budget releases, bank statements, employee records and evidence of salary receipt. Particular attention should be paid to suspected ghost workers, duplicate salary payments, unauthorised payroll amendments, unusual beneficiary accounts and unexplained payment reversals.
Beneficiary-level analysis is equally important. Tracing salary disbursements to receiving accounts and examining subsequent transfers may reveal whether funds reached legitimate employees or were diverted through intermediaries. Investigators should also establish who authorised payroll changes, approved disbursements, conducted reconciliations and controlled access to relevant financial systems.
Nigeria’s broader experience demonstrates the materiality of payroll fraud risks. In July 2026, Channels Television reported that the Independent Corrupt Practices and Other Related Offences Commission (ICPC) had identified 908 suspected ghost workers across at least 50 federal ministries, departments and agencies and recovered approximately ₦942 million linked to fraudulent payroll payments. This separate investigation underscores the importance of employee verification and payroll controls but does not establish any connection to the Court of Appeal allegation.
AML, Sanctions and Enforcement Considerations
An unexplained public-sector payment is not automatically evidence of money laundering, corruption or a sanctions violation. Compliance teams must establish the underlying facts before determining whether the circumstances trigger financial intelligence reporting, asset-preservation measures or criminal referrals under applicable law.
Where evidence indicates possible diversion, investigators should trace the movement of funds, identify beneficial owners and intermediaries, assess potential proceeds of crime and determine whether any relevant persons or entities are subject to applicable sanctions. Any potential match requires appropriate identity verification and legal assessment. The available information does not establish that Justice Dongban-Mensem or the Court of Appeal has been sanctioned or found criminally liable in connection with this allegation.
Compliance Implications and Key Takeaways
The immediate compliance priority is independent verification. Investigators and oversight bodies should obtain the underlying audit schedules, payroll records, bank statements, payment approvals and correspondence to establish the amount involved, the period covered and the reasons for any discrepancy. Financial evidence should be preserved under documented chain-of-custody procedures, with confirmed losses distinguished from unsupported expenditure and accounting errors.
The case also highlights the importance of independent payroll reconciliation, employee identity verification, segregation of financial duties, access controls and documented responses to lawful investigative requests. Where evidence supports suspected fraud or corruption, referrals and recovery measures should follow applicable legal procedures, with responsibility attributed only where supported by evidence.

No Comment! Be the first one.