


NAICOM Tightens Insurance Licensing, Makes PEP Screening Mandatory
The National Insurance Commission (NAICOM) has introduced stricter anti-money laundering and counter-terrorism financing requirements for insurance companies, making documented Politically Exposed...
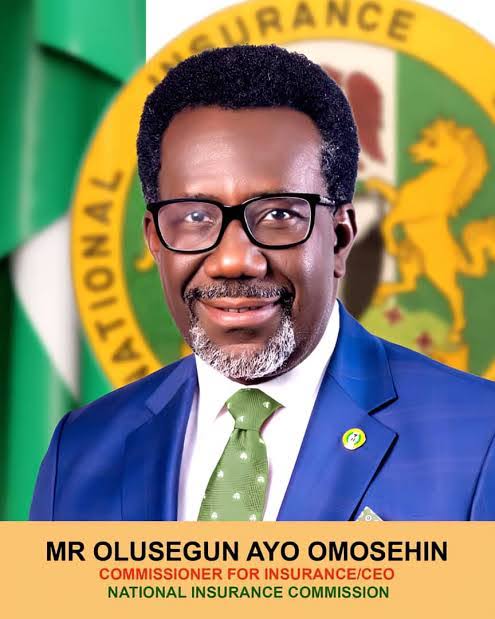
The National Insurance Commission (NAICOM) has introduced stricter anti-money laundering and counter-terrorism financing requirements for insurance companies, making documented Politically Exposed Person (PEP) management procedures compulsory for new licence applications and licence renewals.
The directive, issued after the insurance sector’s recapitalisation exercise, is contained in a circular titled AML/CFT/CPF Addendum to the Guidelines on Licensing and Renewal of Insurance Institutions’ Licences in Nigeria.
Under the new requirements, insurance institutions and prospective applicants must submit an enterprise-wide Anti-Money Laundering, Countering the Financing of Terrorism and Countering Proliferation Financing (AML/CFT/CPF) programme approved by their boards or promoters.
The programme must cover customer due diligence, beneficial ownership identification, PEP management, sanctions screening, suspicious transaction reporting, staff training, independent compliance reviews and record-keeping procedures.
NAICOM is also requiring applicants to disclose their ultimate beneficial owners, ownership and control structures, nominee arrangements and persons with significant control.
In addition, companies must provide evidence that significant shareholders, beneficial owners, directors and principal officers have been screened against criminal databases, PEP databases, sanctions lists, terrorism lists, relevant watchlists and adverse media sources.
Applicants must also demonstrate the source of capital, source of funds and source of wealth of promoters and investors.
The new requirements reinforce NAICOM’s regulatory focus on ensuring that only institutions with adequate governance, financial transparency and compliance frameworks receive or retain operating licences.
Compliance Takeaway
The directive represents a significant shift from treating AML compliance as an operational requirement to making it a condition of market entry and continued regulatory approval.
For compliance professionals in the insurance industry, PEP screening must be supported by documented risk assessments, enhanced due diligence, source-of-wealth verification and appropriate senior management oversight.
Organisations should also review their beneficial ownership registers, sanctions-screening systems, transaction monitoring, suspicious transaction reporting procedures and staff training programmes.
Boards and senior management must take ownership of AML/CFT/CPF frameworks rather than leaving compliance responsibilities solely to compliance departments.
The practical message is clear: inadequate AML controls, weak ownership transparency and poor PEP management can now jeopardise an insurance institution’s licensing and regulatory standing.



No Comment! Be the first one.