


Prophet John Papa Raises Church Offering to GH₵50 — But Where Is the Compliance Line?
A Ghanaian pastor’s decision to set a minimum church offering of GH₵50 has triggered an online debate, but the development also raises a broader question for religious organisations: where does...
- Minimum Offering, Raise Governance Questions
A Ghanaian pastor’s decision to set a minimum church offering of GH₵50 has triggered an online debate, but the development also raises a broader question for religious organisations: where does voluntary giving end and institutional financial governance begin?
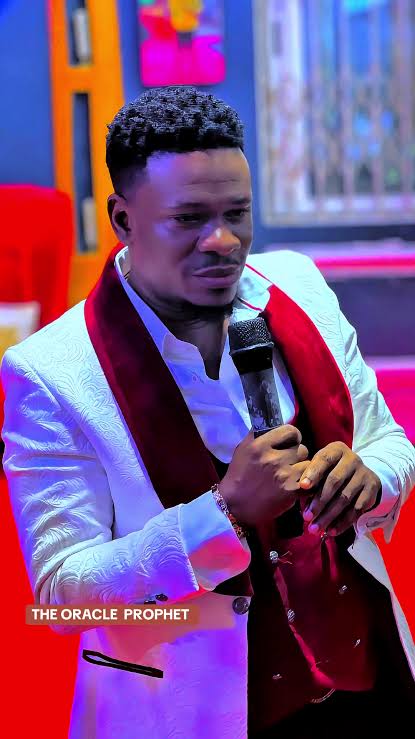
Prophet John Papa Jesus announced that his church would accept only offerings of GH₵50 and above, describing the move as a 20 per cent increase and linking it, in part, to an increase in transport fares. The announcement was made in a video circulated online and subsequently drew public reactions.
From a compliance perspective, the more significant issue is not whether a church chooses to adjust its fundraising practices. It is whether the organisation has adequate governance, financial controls and transparency around money collected from members.
Churches occupy a distinctive position. In Ghana, religious organisations can operate as companies limited by guarantee, a structure that includes churches and other associations. Such entities are subject to corporate governance requirements, including annual returns and financial statements under the applicable framework. Office of the Registrar of Companies
There is also a financial-crime dimension. Ghana’s Financial Intelligence Centre identifies religious bodies among organisations within the broader reporting and anti-money-laundering framework. Its national risk assessment notes that organisations operating in the non-profit sector can face vulnerabilities associated with large cash donations, cross-border funding and weak financial controls.
That does not mean a minimum offering is evidence of wrongdoing. Nor does the reported announcement, by itself, establish any regulatory breach. The compliance question is what happens around the collection and management of those funds.
A properly governed religious organisation should be able to demonstrate who is authorised to collect and control funds, how offerings are recorded, how they reach institutional accounts, who approves expenditure and whether appropriate financial records are maintained.
The issue becomes particularly important where religious authority and financial authority are concentrated in the same individual. Strong internal controls, independent oversight and documented financial procedures can reduce the risk of conflicts of interest and provide greater assurance to members and regulators.
Ghana’s tax framework also makes clear that registration and tax obligations depend on the nature of an organisation’s activities and income; an organisation’s religious or non-profit character does not automatically remove every compliance obligation.
The wider lesson is therefore less about the GH₵50 figure than about accountability for voluntary contributions. As religious organisations handle increasingly significant financial flows, transparency, record-keeping and governance should remain central to maintaining public and congregational trust.

No Comment! Be the first one.