

Ex-Warri Refinery MD Faces Trial Over Alleged ₦1 Billion Money Laundering
Former Managing Director of Warri Refining and Petrochemical Company Limited (WRPC), Jimoh Olasunkanmi Yisawu, is scheduled to face trial before the Federal High Court in Abuja over an eight-count...
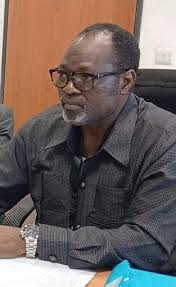
Former Managing Director of Warri Refining and Petrochemical Company Limited (WRPC), Jimoh Olasunkanmi Yisawu, is scheduled to face trial before the Federal High Court in Abuja over an eight-count money-laundering charge filed by the Economic and Financial Crimes Commission (EFCC).
The case, listed before Justice Inyang Ekwo, concerns allegations involving approximately ₦1 billion in suspected proceeds of unlawful activity. A case-tracking record lists the alleged amount as ₦1,000,339,000, while media reports describe the broader alleged scheme as involving approximately ₦1.339 billion. These figures should not be treated as interchangeable without reconciliation against the complete charge sheet.
Allegations Involving Foreign Currency and Third-Party Transactions
According to reports on the prosecution’s case, the EFCC alleged that Yisawu indirectly converted US$789,950 through an individual identified as Samaila Bala between October 2023 and May 2025. Prosecutors reportedly contend that the funds were inconsistent with the defendant’s known lawful earnings as a public officer and constituted proceeds of unlawful activity.
The commission also alleged that Yisawu converted US$122,600 through Rasheed Olaitan Yusuf of Rasheedat Anike Global Ventures between February 2024 and March 2025. Other counts reportedly concern cash transactions conducted outside financial institutions, funds allegedly received from a contractor linked to an NNPC subsidiary, and a transfer of ₦65.86 million to Cordros Securities Limited for the purchase of treasury bills.
The allegations form part of an eight-count charge brought under provisions of Nigeria’s money-laundering legislation. Yisawu pleaded not guilty at his arraignment on 20 July 2026. He was granted bail of ₦500 million, subject to conditions that included a surety, verification of property documents and surrender of his international passport. Reports state that he was to remain in EFCC custody until the bail conditions were fulfilled.
AML/CFT and Financial Crime Compliance Analysis
Potential Money-Laundering Typologies
The alleged use of intermediaries to move substantial sums, together with cash transactions reportedly conducted outside the formal banking system, raises potential concerns about the traceability of funds, the identification of beneficial recipients and the economic rationale for transactions. If substantiated, these features could be relevant to the placement, layering or integration stages of money laundering. However, the available reports do not establish that every transaction formed part of a deliberate laundering scheme.
Source of Wealth and Source of Funds
The prosecution’s reported concern that certain funds were inconsistent with the defendant’s known lawful earnings highlights the importance of source-of-wealth and source-of-funds assessments. In a regulated financial institution, a proportionate review would ordinarily consider the customer’s declared occupation, income, business interests, expected account activity, transaction history and supporting documentation.
Where material discrepancies remain unexplained, institutions should assess whether enhanced due diligence, internal escalation or suspicious transaction reporting is required under the applicable legal and regulatory framework.
Third-Party Payments and Contractor Relationships
The reported transactions involving third parties and a contractor linked to an NNPC subsidiary illustrate the compliance risks that may arise when payments move between public officials, contractors, intermediaries and investment accounts.
Relevant controls include identifying the ultimate beneficial owner, establishing the commercial purpose of payments, verifying contractual relationships, reviewing related-party transactions and investigating unusual payment instructions. Public-sector exposure may also warrant assessment under applicable politically exposed person (PEP) controls, depending on the person’s status, the institution’s obligations and the relevant risk factors.
Cash Transactions and Transaction Monitoring
The alleged cash payments warrant attention to applicable cash-transaction restrictions, recordkeeping requirements and reporting obligations under Nigerian law. Compliance teams should examine whether transactions were properly documented, whether financial institutions were bypassed and whether the pattern of activity was consistent with the stated purpose of the funds.
Transaction monitoring should assess the substance and cumulative value of activity rather than relying exclusively on individual transaction thresholds. Any determination that reporting obligations have been triggered must be made under the applicable rules and supported by the institution’s assessment.
Treasury Bills and the Movement of Funds into Investments
The alleged transfer of ₦65.86 million to purchase treasury bills illustrates why investment transactions may require scrutiny beyond the product itself. Treasury bills are legitimate financial instruments, and their purchase does not independently establish money laundering. The relevant compliance questions concern the origin of the funds, the identity of the beneficial investor, the transaction’s purpose and whether the investment activity was consistent with the customer’s financial profile.
Governance and Public-Sector Accountability
The prosecution is also relevant to governance and financial controls within state-owned enterprises and the wider petroleum sector. Where allegations concern transactions involving former public officials and contractors, effective controls should include segregation of duties, documented procurement decisions, conflict-of-interest management, independent payment approvals and auditable records of contractor disbursements.
The proceedings may help establish whether the transactions identified by prosecutors can be substantiated through documentary evidence and witness testimony. Until the court reaches its findings, the allegations should not be treated as proof that public funds were misappropriated or that the defendant committed a criminal offence.
Current Case Status and Compliance Implications
As of 26 October 2026, the case-tracking record identifies the matter as being at the prosecution stage and lists 26 October as the next sitting date. Media reports have identified 26–28 October as the scheduled trial period. The outcome of the 26 October sitting, including whether the trial commenced or was adjourned, should be confirmed from an updated court record or a reliable report before publication.
For financial institutions, compliance officers, AML/CFT analysts and corporate risk teams, the case illustrates the importance of evidence-led adverse-media reviews. Any risk assessment should distinguish between the existence of a formal charge, the prosecution’s allegations, verified transaction evidence and the eventual judicial outcome.
A proportionate compliance response may include reviewing relevant customer or counterparty relationships, checking applicable sanctions and PEP requirements, validating source-of-funds documentation, assessing transaction-monitoring alerts and documenting decisions in line with internal policies and applicable law. The existence of a pending criminal case should not automatically be equated with a conviction or treated as sufficient, on its own, to justify every form of account restriction or relationship termination.

No Comment! Be the first one.