


Fact-Check: Did Peter Obi’s Administration Leave Anambra With $123.77m in External Debt?
A claim that former Anambra State Governor Peter Obi left office with $123.77 million in outstanding external debt requires important clarification when examined against official debt records....
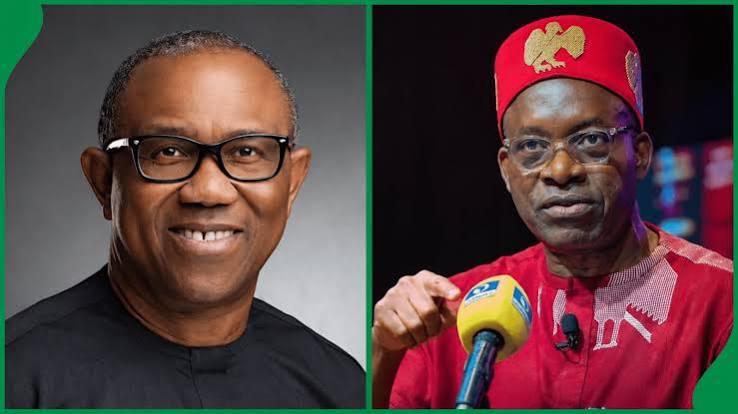
A claim that former Anambra State Governor Peter Obi left office with $123.77 million in outstanding external debt requires important clarification when examined against official debt records.
The Anambra State Government has said that eight external financing facilities associated with projects undertaken during Obi’s administration had a combined contracted value of $123.77 million. The figure has subsequently been presented as part of the financial obligations inherited by succeeding administrations.
However, the contracted value of a loan facility is not necessarily the same as the amount outstanding when an administration leaves office.
Official figures from the Debt Management Office (DMO) show that Anambra State’s external debt stood at $30.32 million as of December 31, 2013. Obi remained governor until March 17, 2014. The next available DMO record, covering June 30, 2014, placed the state’s external debt at $41.46 million.
The figures are therefore materially different from the $123.77 million being cited by the state government. The difference is significant from a financial-compliance perspective because a loan facility can have a total approved or contracted value that is substantially higher than the amount actually disbursed and outstanding at a particular point in time.
Determining whether the entire $123.77 million should be attributed to Obi’s administration would require a facility-by-facility reconciliation of the financing arrangements. That reconciliation would need to establish when each facility was approved and signed, how much was actually disbursed before March 17, 2014, what amounts were disbursed after the handover, and the principal and other obligations outstanding on the date Obi left office.
This distinction is important in public-sector financial reporting. A government may enter into a financing agreement for a particular project without immediately drawing the entire amount available under the facility. Subsequent administrations may also draw down undisbursed portions of an existing facility and assume responsibility for repayments.
The available DMO records establish that Anambra had external debt during Obi’s tenure. The December 2013 debt stock was $30.32 million, while the June 2014 figure was $41.46 million. What those records do not establish, however, is that $123.77 million was outstanding as debt when Obi left office.
The $123.77 million figure appears to represent the aggregate contracted value of eight external financing facilities rather than the debt stock recorded against Anambra at the time of the March 2014 transition.
Obi has disputed the characterisation of the facilities, saying he did not personally borrow or issue bonds for Anambra and challenging the use of the $123.77 million figure to describe the state’s debt position at the end of his administration.
From a compliance and accountability standpoint, the most reliable way to resolve the dispute is through publication of the underlying loan agreements, disbursement schedules, project-utilisation records, repayment statements and the state’s debt position as of March 17, 2014.
Verdict
The claim that Peter Obi’s administration left Anambra with $123.77 million in outstanding external debt is misleading without further qualification.
The $123.77 million figure relates to the aggregate value of the identified financing facilities, while available DMO records show considerably lower external debt stocks around the period of the 2014 transition. A definitive attribution of the full $123.77 million to Obi’s administration would require evidence showing how much of each facility had actually been drawn and remained outstanding when he left office.
The distinction between loan commitments, actual disbursements and outstanding debt is central to any accurate assessment of the claim and is also a fundamental consideration in public-sector financial accountability.

No Comment! Be the first one.